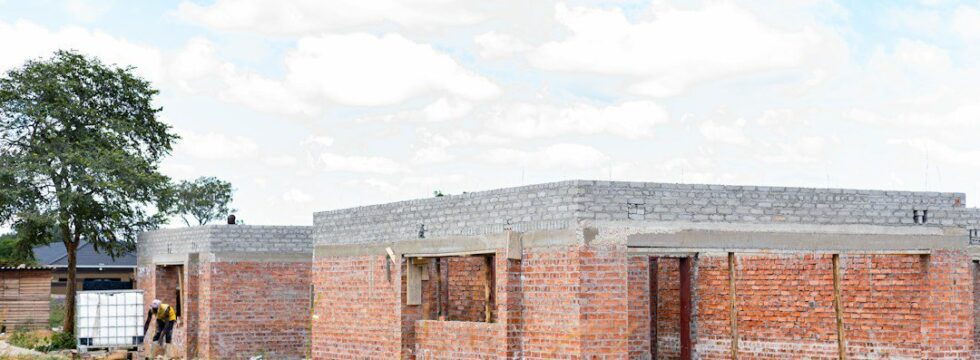
A partially completed building is genuinely worth considerably less than either the land it sits on or the finished scheme – which is exactly why a stalled development represents every lender’s worst nightmare, and precisely why cost overruns are treated as seriously as they are. Understanding how the mechanics genuinely work before you’re facing an overrun matters far more than discovering them mid-build.
Why Contingency Is Consumed First, Not Held in Reserve
Our UK Development Finance hub covers the wider lending landscape; this piece focuses specifically on what genuinely happens once costs exceed the approved budget. Most facilities include a contingency of 5-10% of build costs, held within the facility itself and released on monitoring surveyor instruction. It’s worth understanding this contingency is the first thing consumed when costs run over – not a separate reserve sitting untouched until a genuine emergency.
What Happens Once Contingency Is Genuinely Exhausted
Once the contingency is used up, you as the developer must inject additional equity or find supplementary finance to complete the project. If neither is genuinely available, the development stalls – and it’s worth understanding a stalled scheme is a fundamentally worse outcome for everyone than a delayed but completed one, since the security itself, a partially built asset, is worth meaningfully less than either the land or the completed development.
The Dual Cap That Determines Your Real Ceiling
Lenders apply two separate caps simultaneously – Loan to Cost, typically 75-90% of total development cost, and Loan to GDV, commonly 65-70% of the completed scheme’s value – advancing whichever figure is genuinely lower. On a £1.2 million total project cost at 85% LTC, the maximum facility is £1,020,000, requiring you to fund the remaining £180,000 from equity from the outset. A cost overrun genuinely pushes your total cost figure up, which can pull your maximum facility further away from what you actually need, not simply require a top-up of the shortfall alone.
Why Lenders Genuinely Require a Formal Review Before Releasing Further Funds
When actual costs exceed the original budget, most lenders require a formal review before releasing further tranches, assessing revised costs to complete, the genuine impact on overall scheme viability, and whether additional equity is genuinely needed to restore the required coverage. This isn’t a formality – it’s a genuine re-underwriting of whether your scheme remains viable at all under the new cost position.
Why Facility Documentation Genuinely Gives Your Lender the Right to Pause Everything
It’s worth understanding your facility agreement typically gives the lender clear contractual rights to halt further drawdowns, re-test overall scheme viability, and require additional equity before releasing another pound – without this, a lender could otherwise be forced to keep funding into a genuinely failing project, or face a half-built asset on enforcement instead. This is worth reading carefully in your own documentation before you sign, since it defines exactly what your lender can and can’t do the moment costs genuinely start running over.
The Single Factor That Genuinely Determines the Outcome
Proactive disclosure to your lender allows structured solutions to be genuinely agreed; surprises discovered only at the drawdown stage tend to trigger considerably more defensive responses instead. It’s worth understanding this isn’t simply good etiquette – lenders who are kept properly informed are genuinely far more likely to offer standstill arrangements or restructuring options than ones who discover a problem through a stalled drawdown request.
The Genuine Most Common Causes Worth Understanding
Inadequate initial budgeting is genuinely the most frequent cause – developers, particularly earlier in their careers, often build cost plans around the most optimistic assumptions, lowest tender prices with no allowance for genuine contingency scenarios. Labour and material cost inflation has made overruns considerably more common since 2022, and contractor insolvency mid-build is a further genuine risk, since replacing a main contractor partway through a scheme is expensive, slow, and frequently triggers a cost overrun in its own right.
Why Mezzanine Finance Is Often the Genuine Bridge to Completion
Our Mezzanine Finance page covers layering additional debt behind your senior facility specifically for this scenario, worth discussing early with your broker rather than only once contingency has genuinely run out, since a mezzanine facility arranged calmly ahead of time is considerably easier to secure than one arranged under genuine time pressure.
Why a Stretched Senior Structure Can Sometimes Absorb More Headroom
Our Stretched Senior Debt page covers a single, higher-leverage facility reaching further into your total cost requirement than standard senior debt alone; it’s worth understanding this structure from the outset if your scheme’s margin is genuinely tight enough that even a modest overrun could otherwise be difficult to absorb.
Why Refurbishment Schemes Face a Genuinely Elevated Overrun Risk
Our Refurbishment Loans page covers works on existing buildings specifically, worth reading alongside this piece since contingency requirements here often sit higher than the standard 10% minimum, reflecting the genuine additional uncertainty that comes with unknown conditions behind existing walls and structures.
Restructuring Your Facility if an Overrun Genuinely Occurs
Our Structured Property Finance page covers tailoring a facility to genuinely reflect your specific circumstances, worth discussing if your scheme needs restructuring mid-build rather than assuming your original facility terms are fixed regardless of how the project has evolved.
Getting Ahead of a Potential Overrun Before It Becomes One
Given how much genuinely depends on early, honest communication with your lender the moment cost pressure first appears, it’s worth having a proper conversation about your realistic contingency and supplementary funding options before you commit to a specific facility structure. Get in touch with details of your scheme and current cost position, and we’ll help you understand your genuine options.
Frequently Asked Questions
What happens when my development finance contingency runs out?
You’ll need to inject additional equity or secure supplementary finance to complete the project – without either, the development genuinely risks stalling.
Will my lender automatically release more funds if I need them?
No – most lenders require a formal review of revised costs to complete and overall scheme viability before releasing any further tranches beyond the original facility.
Can my lender simply refuse to release any further money at all?
Yes, genuinely – most facility agreements give the lender contractual rights to halt drawdowns and require additional equity before continuing, worth reading carefully in your own documentation.
How much contingency should I build into my original budget?
Commonly 5-10% of build costs as a minimum, though refurbishment or conversion schemes often warrant a higher figure given the additional uncertainty involved.
Does telling my lender about a potential overrun early genuinely help?
Yes, considerably – proactive disclosure allows structured solutions to be agreed, while surprises discovered at drawdown stage tend to trigger far more defensive responses.
What’s the most common cause of cost overruns on development schemes?
Inadequate initial budgeting, commonly based on overly optimistic tender prices with insufficient allowance for realistic overrun scenarios.
Get in touch with details of your scheme and current cost position, and we’ll help you understand your genuine options before an overrun becomes a genuine crisis.